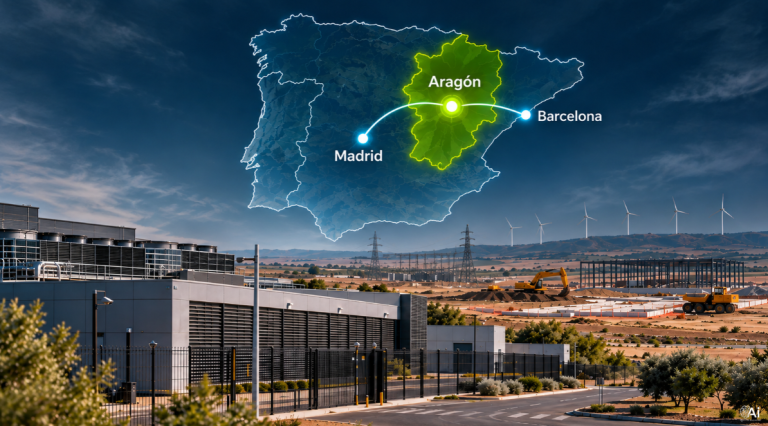

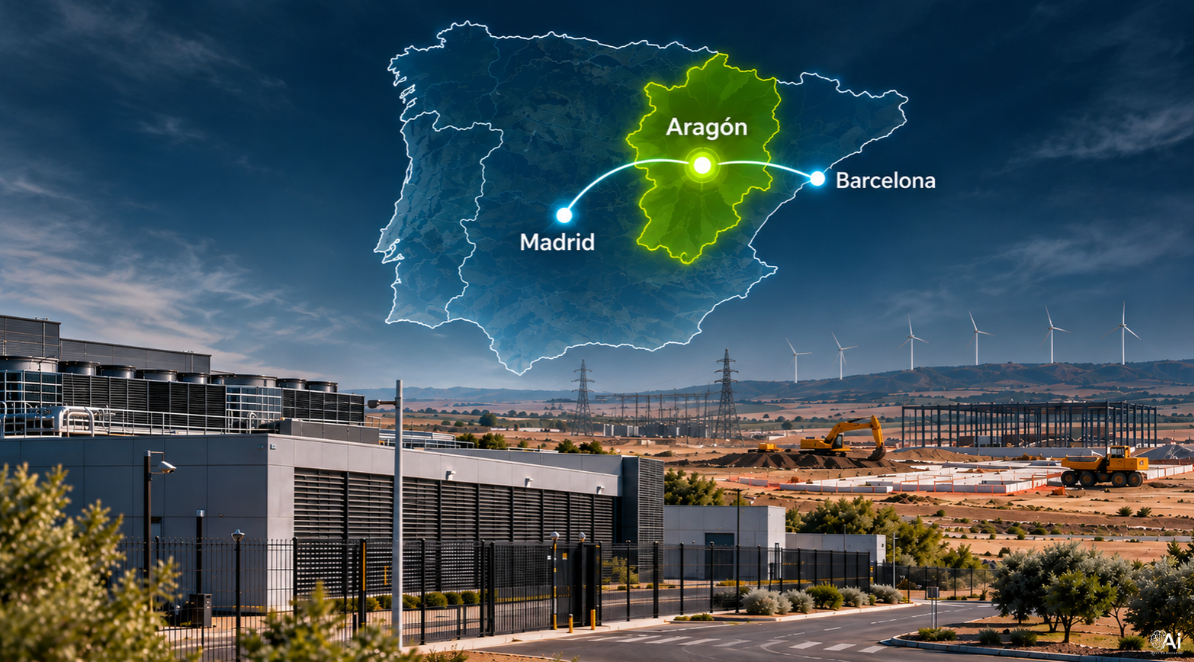
Spain’s data-centre map used to be a straightforward Madrid-and-Barcelona story. That is no longer true. Earth-moving equipment is already working on large sites around Zaragoza, Calatorao and La Muela, while Madrid’s existing halls still carry most of the live load. Whether those projects deliver real megawatts, or stay on paper, is what matters next.
Where Is Spain’s Data Centre Capacity Landing?
Madrid still holds the largest share of operating IT capacity, while Aragón carries most of the announced pipeline and Barcelona functions mainly as a connectivity node. Live load and future capacity are different numbers and cannot be read as the same thing.
Madrid and surrounding municipalities
Colliers recorded 212 MW IT in the Madrid market in its April–September 2026 snapshot, up from 175 MW IT earlier in the year. Capacity sits across several sites rather than in one campus:
- Apto is advancing a campus in Fuenlabrada on a former industrial site. It has already completed a 40 MW on-site substation and plans up to 240 MW across five buildings.
- Iron Mountain is expanding its San Fernando de Henares facility. MAD-1 currently runs at 3 MW; the campus is approved for up to 79 MW IT.
- Equinix and Data4 have operational halls in Alcobendas.
- MERLIN–Edged is active in Getafe.
Aragón
Aragón has around 108 MW IT operational against a future pipeline of 3,764 MW IT. The pipeline figure includes projects at widely different stages. Named locations cluster around Zaragoza province and Huesca:
- AWS is expanding across municipalities that include Zaragoza, Huesca, Villanueva de Gállego, El Burgo de Ebro and La Sotonera, with later phases reaching into Teruel. The AWS Europe (Spain) Region has operated from the region since November 2022.
- Microsoft’s three campuses are planned for La Muela, Villamayor de Gállego and the Zaragoza municipality near Puerto Venecia. Site preparation is under way at the Zaragoza location.
- QTS is developing a 224-hectare site in Calatorao under Project Rhodes. Aragón’s government granted partial PIGA approval for urbanisation and supporting infrastructure in September 2026.
- MERLIN–Edged’s Zaragoza-WIND project is located in Botorrita (144 MW IT design).
Barcelona and secondary locations
Barcelona added capacity through Digital Realty’s BCN1 opening and Templus expansions, reaching 63 MW IT. The city’s role is more connectivity-driven than hyperscale volume:
- Digital Realty opened BCN1 in Sant Adrià de Besòs on May 18 2026, with 14 MW total planned capacity, and has positioned it as a Mediterranean interconnection point.
- Further afield, Meta’s proposed campus is in Talavera de la Reina in Toledo. Land milestones are confirmed; construction has not started.
- MERLIN–Edged has an existing site at Rivabellosa in Álava.
Madrid delivers most of the working capacity today. Aragón absorbs the largest named commitments and future pipeline. Barcelona adds interconnection rather than bulk IT load.
Who Is Building the Major Projects
Named commitments are concentrated in a handful of large programmes rather than spread evenly across the market. The figures below reflect company statements and confirmed public milestones; they are not a full accounting of every site in the pipeline.
- Amazon raised its planned investment in Spain to €33.7 billion in March 2026. That adds €18 billion to the €15.7 billion announced earlier and supports expansion of the AWS Europe (Spain) Region (open since November 2022) plus related infrastructure, including server manufacturing facilities in Aragón.
- Microsoft is advancing three campuses in Aragón through its local promoter 7724 Spain. Company statements put the programme at roughly €5.356 billion. Environmental filings for the La Muela campus cite 345.6 MW. Site preparation is already under way at the Zaragoza location; geotechnical work has been reported at the other two.
- QTS is developing the Calatorao campus on 224 hectares with backing from funds managed by Blackstone affiliates. The company describes it as a multi-billion-euro commitment. Aragón’s government granted partial final approval to the PIGA for urbanisation and supporting infrastructure in September 2026.
- Apto has estimated up to €2 billion for its Fuenlabrada campus of up to 240 MW across five buildings. Enabling works and a 40 MW on-site substation are already complete.
- MERLIN Properties, with Edged as technology partner, has specified €1.225 billion for the announced 144 MW IT design at Botorrita.
- Meta’s proposed campus in Talavera de la Reina is promoted through Zarza Networks. Regional authorities have confirmed land-related milestones and a figure of €750 million; construction has not started.
These are the largest publicly quantified commitments. Several other projects remain in the pipeline at earlier stages or without equivalent public investment figures.
Why These Locations?
Aragón offers cheap renewable power (82.9 per cent of 2025 generation, per Red Eléctrica), large land parcels and faster permitting via PIGA status. AWS has run its Spanish region from the area since November 2022.
Madrid already has the cloud market, dense fibre and industrial sites, though power and grid access remain the main constraints.
Barcelona is mainly about interconnection. Digital Realty has positioned BCN1 to complement its Marseille campus, with subsea cables such as 2Africa and Medusa landing nearby.
What Is Moving Versus What Is Still Announced
Operating capacity is concentrated in Madrid and, to a lesser extent, Barcelona and the existing AWS region. Digital Realty announced the opening of BCN1 on May 18 2026 and described 14 MW as total planned capacity. Iron Mountain’s MAD-1 in San Fernando de Henares is operating at 3 MW current capacity, with the campus approved for up to 79 MW IT across phased buildings.
Site works are under way or complete at several locations, but most large projects still need further approvals before full construction.
- At Calatorao, earthworks for the QTS project were imminent or beginning after the September 2026 partial PIGA approval, according to local reports.
- Apto has completed enabling works and a 40 MW on-site substation at Fuenlabrada. A July agreement assigns IGNIS responsibility for further connection infrastructure and renewable self-consumption.
- AWS has recorded partial final approvals for phase-one building works, internal development and substations.
- Microsoft’s environmental documentation was still being processed in the autumn of 2026. Site preparation and earth-moving have been reported at its Zaragoza location.
- Meta’s September update confirmed a land-related guarantee after August reparcelation approval. No construction has taken place.
These steps show movement on enabling works and early approvals. Full building construction on the largest campuses still depends on remaining permits and grid connections.
Key Projects by Location, Capacity, Investment and Status
What This Means for Capital and What to Watch Next
Delivery is phased. Land control, planning approvals and substations can advance for years before a first data hall opens, and a first building can operate long before the full campus is complete. Announced investment figures are not capital already spent, and full-campus MW totals are not near-term supply. Projects that have completed substations and secured demand permissions are further along than those still awaiting environmental clearance or land guarantees.
The next signals to watch are first-building ready-for-service dates, the size of granted grid access relative to announced IT load, progress on renewable power purchase agreements, and the final shape of national rules on data-centre development. Microsoft has indicated it expects the first phase of its Aragón campuses to take up to four years once the PIGA is fully approved; QTS has pointed to initial buildings around 2028.
Those dates, and the grid connections that sit behind them, will show how much of Spain’s pipeline actually arrives as working capacity.
Author: Connor Fitzgerald
See Also:
What Country in Europe Has the Most Data Centres?
Largest Data Centres in the World: The Gigawatt Club (2026)
Where Will Europe Actually Put Its Data Centres?
Frequently Asked Questions
Madrid holds the largest share of operating capacity, while Aragón carries most of the announced pipeline. Barcelona is mainly a connectivity hub.
It offers high renewable generation (82.9% of 2025 output), large land parcels and faster permitting through PIGA status. AWS has operated its Spanish region from the area since 2022.
Colliers recorded 212 MW IT in Madrid, 108 MW IT in Aragón and 63 MW IT in Barcelona in its April–September 2026 snapshot.
AWS, Microsoft, QTS (Blackstone-backed) and Apto are among the largest named commitments, focused on Aragón and the Madrid area.
Microsoft has indicated its first phase could take up to four years once full PIGA approval is secured. QTS has pointed to initial buildings around 2028. Most large campuses remain phased.