
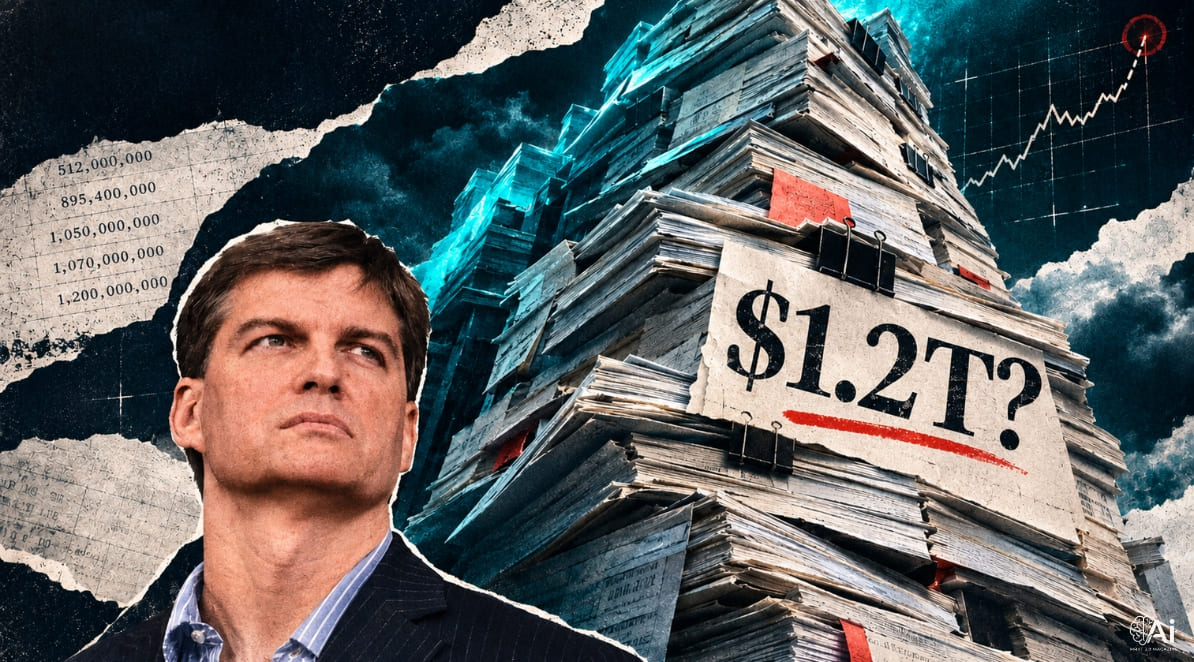
Michael Burry has gone through Anthropic’s amended S-1 and come away with a higher number than the company itself disclosed. Burry puts the total commitments at $1.05 trillion to $1.07 trillion, and says they could approach $1.2 trillion. Anthropic’s own figure is $895.4 billion. The company filed the S-1/A on November 2, adding third-quarter numbers.
Burry is best known for correctly betting against the US housing market before the 2008 financial crisis, the trade that made him the central figure in “The Big Short.” Since then his crash calls have been pretty mixed. He has repeatedly warned of major market collapses (including a 2023 “Sell” tweet he later said was wrong) that did not materialise. Despite some of his misses, his work is still closely followed.
What Does Burry Say Is Missing from the Total?
Burry argues the $120.5 billion SpaceXAI contract is left out of the S-1’s main obligation tables, which only include non-cancellable contracts. On his reading, true commitments over the next 12 months could exceed $100.8 billion, not the $69.8 billion reported. His projected payments run roughly $101 billion in 2027, $112 billion in 2028 and $127 billion in 2029.
That would require about 11.6% sequential monthly revenue growth through 2027 just to cover the commitments. For a 20% GAAP margin he puts the required rate at 16.1%.
“Anthropic published a number. $895.4 billion. Which may even amount to nearly $1.2 trillion in commitments just from this one company that the optimists say will do $100 billion in revenue the next 12 months,” Burry wrote.
“That kind of growth is mandatory. Not only is the company priced for optimism, it is betting its entire existence on that optimism, that kind of supranormal growth.”
Why the Slower Growth Matters
Anthropic’s sales rose 47% sequentially in the third quarter, versus 144% in the second and 132% in the first. Burry links the slowdown to fading “tokenmaxxing” (aggressive token-usage strategies that previously boosted consumption), citing press reports. He also flags Anthropic Direct, the company’s plan to build and run its own computing capacity, as something that raises longer-term liabilities.
The gap between the disclosed figure and Burry’s higher one sits inside a larger question about whether the current pace of AI infrastructure spending can hold. Ken Griffin recently said investors are “almost certainly” in an AI bubble; we covered that here.
Similar questions hang over neocloud contracts. Nscale, for example, has signed large deals with Anthropic and Microsoft against limited live power.
Aswath Damodaran cut his Anthropic equity value estimate to $1.45 trillion from $1.475 trillion while keeping a $100 billion 12-month revenue projection. Burry has said he will not seek an allocation in the IPO and will not become a shareholder later.
Governance and Control
Founder LLC’s Class F share will carry 50.1% of the voting power, the S-1/A says, while each Class A share has one vote. Class F is issued immediately before the offering completes. Class T stock elects Class T directors (a majority of the board), and the Long-Term Benefit Trust holds that stock. Anthropic will be a controlled company under Nasdaq rules. It has applied to list Class A on the Nasdaq Global Select Market under the ticker ANT.
Author: Grace Sharp