
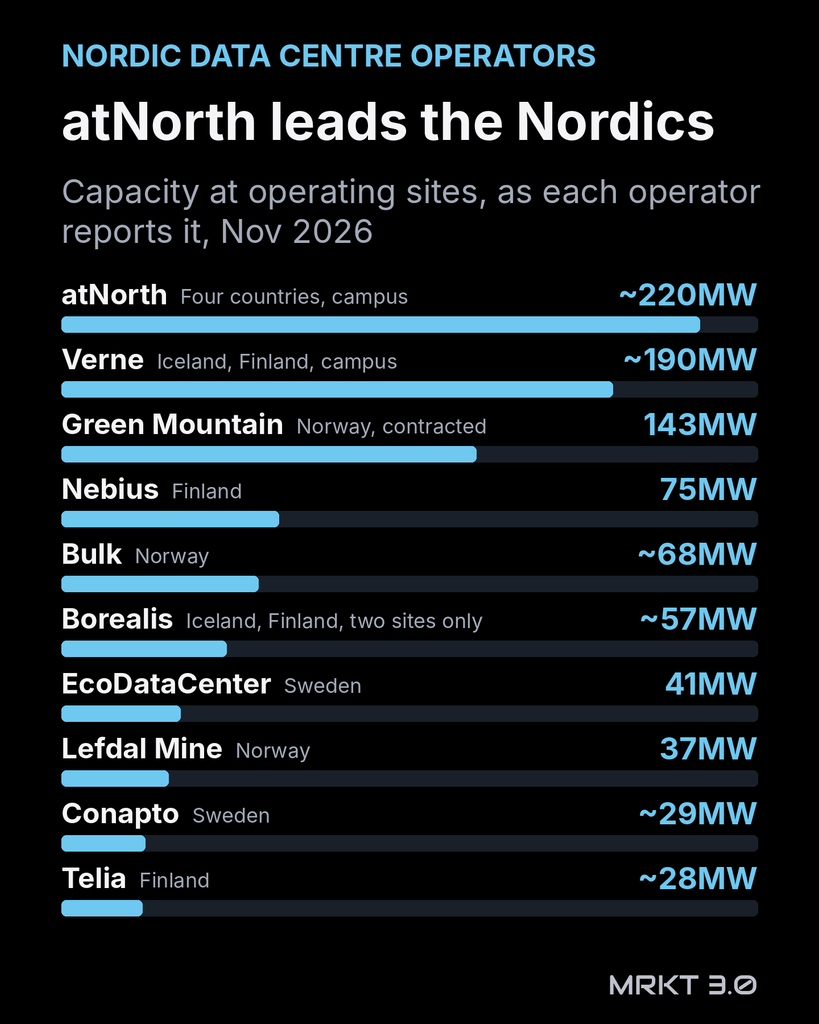
On published figures, atNorth is the biggest of the Nordic data centre operators that rent capacity to others, with about 220MW across eight sites, ahead of Verne and Green Mountain. The top three are closer than they look: atNorth’s and Verne’s figures are campus totals, while Green Mountain’s 143MW is capacity customers have signed for at operating sites.
| Operator | Countries | Capacity | Next | |
|---|---|---|---|---|
| 1 | atNorth | Iceland, Sweden, Finland, Denmark | about 220MW (campus) | Kouvola: up to 430MW, from 2027 |
| 2 | Verne | Iceland, Finland | about 190MW (campus) | Mäntsälä: 70MW |
| 3 | Green Mountain | Norway | 143MW (contracted) | Undheim: 80MW, 2028 |
| 4 | Nebius | Finland | 75MW | 380MW, from 2027 |
| 5 | Bulk | Norway, Denmark | about 68MW | More N01 buildings planned |
| 6 | Borealis | Iceland, Finland | about 57MW (two sites) | Blönduós expansion |
| 7 | EcoDataCenter | Sweden | 41MW | Falun to 65MW; Borlänge, 2027 |
| 8 | Lefdal Mine | Norway | 37MW | 43MW |
| 9 | Conapto | Sweden | about 29MW | Stockholm 5: about 28MW, 2027 |
| 10 | Telia | Finland | about 28MW | Not disclosed |
Capacity is the figure each operator gives for sites it says are operating, mostly IT load. atNorth’s is our sum of the campus power capacity on its site pages, and Verne’s is the campus IT capacity on its data sheet, so both may include space not yet fitted out. Big Tech’s own campuses and bitcoin mines are not ranked; both are covered below.
Who Are the Biggest Data Centre Operators in the Nordics?
atNorth, Verne and Green Mountain, with about 550MW between them. After them come Nebius at 75MW and Bulk at about 68MW, and nobody else reaches 60MW.
1. atNorth: about 220MW
atNorth runs eight data centres: three in Iceland, three around Helsinki, one in Stockholm and one near Copenhagen. Its site pages list about 220MW of power capacity between them. However, atNorth does not say how much of that is built out.
CPP Investments, Equinix and Partners Group completed their $4 billion purchase on September 2. CPP now holds about 51%, Equinix 34% and Partners Group, the seller, 10%. Next comes a campus of up to 430MW at Kouvola in Finland, with the first building due in summer 2027. Meanwhile, CoreWeave, the biggest of the neocloud companies, said in late October that most of its planned 22.5MW at atNorth’s Copenhagen site was online.
2. Verne: about 190MW
Verne, owned by the French investor Ardian, runs one of the two biggest campuses on paper in the region, at Keflavík in Iceland. Its data sheet gives the campus more than 140MW of IT capacity, but Verne does not say how much is in use. The one confirmed figure is the 7.5MW that Nscale, a British AI cloud, deployed there this spring.
Its Helsinki campus offered up to 50MW in early 2025. In June, it also started building the first 70MW of a new campus at Mäntsälä, north of Helsinki.
3. Green Mountain: 143MW
Green Mountain, owned by Israel’s Azrieli Group, runs four campuses in Norway. At the end of March, customers had contracted 143MW of capacity at them, Azrieli’s investor presentation shows. That includes 90MW at Hamar, all of it used by TikTok, and 26MW at Enebakk near Oslo. In addition, Undheim, an 80MW campus that is already contracted, is due in 2028.
4. Nebius: 75MW
Nebius, the Amsterdam-based AI cloud, runs 75MW at Mäntsälä after an expansion finished this year. However, it is building far more than it runs. A 310MW campus at Lappeenranta and a second, 70MW building at Mäntsälä both open from 2027. That would take Nebius to 455MW in Finland.
5. Bulk: about 68MW
Bulk Infrastructure, controlled by the Norwegian group Bulk Industrier, runs about 68MW in Norway by our count. That is 54MW in two buildings at its N01 campus near Kristiansand, both full, and 14MW at OS-IX in Oslo. It gives no figure for its DK01 site at Esbjerg, and is planning more buildings at N01.
6. Borealis: about 57MW
Borealis Data Center runs three sites in Iceland, at Blönduós, Reykjavík and Fitjar near Keflavík, and one at Kajaani in Finland. Trade reports give figures for Blönduós and Fitjar that add up to about 57MW; the other two are not included. In June, it also signed for 12MW more firm power from Landsvirkjun to expand Blönduós for AI work. Borealis does not publish a total, so this is the least certain entry.
7. EcoDataCenter: 41MW
EcoDataCenter, owned by the Swedish investor Areim, had 41MW running at Falun at the end of 2025, its annual report says. Two more halls are due to take Falun to 65MW by the end of 2026. In February, Mistral AI also agreed a €1.2bn deal for an AI data centre at its new Borlänge campus. The site has access to 250MW and opens in 2027.
8. Lefdal Mine: 37MW
Lefdal Mine Datacenter, built inside a former mine in western Norway, had 37MW in operation in March, with another 43MW contracted and under construction. 3i Infrastructure completed its investment by early September; with co-investors, 3i manages about 90% of the equity.
9. Conapto: about 29MW
Conapto, owned by the infrastructure fund Marguerite, runs four sites in Stockholm. By our count of the figures it gave in January, they have about 29MW of IT load. Stockholm 4 is the largest, at 18MW. A fifth site, with about 28MW of IT, opens its first half in 2027.
10. Telia: about 28MW
Telia, the Swedish telecoms group, has about 28MW installed in Helsinki after a 4MW expansion due in early 2025, trade reports say. Its own page still gives 24MW of IT power.
Who Else Runs Data Centres in the Nordics?
Several big names do not publish how much capacity is in use, so we cannot rank them.
- Equinix has eight sites in Helsinki and Stockholm, as well as its 34% of atNorth.
- Digital Realty has ten in Stockholm and Copenhagen, including the home of Denmark’s Gefion AI supercomputer.
- STACK lists 58MW at sites in Oslo and Stockholm and a 72MW campus in Copenhagen, but does not say which are built.
- GlobalConnect says it has about 50MW “installed or ready for development”.
- Vaultica, the former STACK colocation business owned by Apollo funds, gives no total.
Just below the top 10 are Glesys, with about 17MW of site power in Sweden and Finland by our count, and Polar, which went live with 12MW at Tørdal in Norway in October for the US AI cloud Crusoe. Nscale’s website says its Glomfjord site has 30MW operating, but Bloomberg reported in October that only 6.4MW was running.
Why Aren’t Meta, Google and Microsoft Ranked?
Because they do not publish how much power their Nordic campuses use. Their sites are probably among the biggest in the region. For example, Microsoft said in 2024 that it would spend SEK 33.7 billion on its Swedish data centres over two years.
| Company | Nordic campuses | Status |
|---|---|---|
| Meta | Luleå (Sweden), Odense (Denmark) | Live; no MW published |
| Hamina (Finland), Fredericia (Denmark), Skien (Norway), Horndal (Sweden) | Hamina and Fredericia live; Skien due 2026; Horndal due 2028; Finnish expansion partly halted | |
| Microsoft | Gävle, Sandviken, Staffanstorp (Sweden); Høje-Taastrup, Køge, Roskilde (Denmark); Espoo area (Finland) | Sweden live; Denmark opened March 26, 2026; Finland’s first phase finished around the turn of the year |
| Apple | Viborg (Denmark) | Live since 2020 |
| Amazon (AWS) | Västerås, Eskilstuna, Katrineholm (Sweden) | Live; no MW published |
What Is the Largest Data Centre in the Nordics?
By published figures, it was Bitdeer’s Tydal site in Norway, which had 175MW of capacity as a bitcoin mine. Bitdeer is now turning the site into an AI data centre, with 121MW of IT capacity due in two phases from the end of 2026. We leave bitcoin mines out of the ranking because they do not rent capacity to others. Among sites that do, Verne’s Keflavík and Green Mountain’s Hamar have the most capacity on paper, more than 140MW and 150MW. Hamar also has the most confirmed in use, 90MW.
How Much Is Being Built?
Cushman & Wakefield counts about 2.1GW in operation across Scandinavia, 20% more than a year earlier, and more than 3GW in planning. As a result, the Nordics are one of the places Europe’s AI build is moving to as the FLAP-D hubs run short of power.
| Project | Country | Size | Stage |
|---|---|---|---|
| Nebius, Lappeenranta and Mäntsälä | Finland | 380MW | Being built, from 2027 |
| Nscale, Kvandal near Narvik | Norway | 100MW | Being built for Microsoft, due 2027 |
| Bitdeer, Tydal | Norway | 121MW | Conversion to AI, from end-2026 |
| Pure DC, Seinäjoki | Finland | 110MW | Being built, fully leased |
| Brookfield, Strängnäs | Sweden | 750MW | Planned; grid not secured |
| Sesterce, Kaipola | Finland | 600MW | Planned; 200MW first phase |
| DayOne, Klaukkala | Finland | Up to 560MW | Planned; no final decision |
| Prime, Esbjerg | Denmark | 550MW | Planned; work could start 2027 |
Why Is So Much Stuck on Paper?
In Denmark, data centres had asked for 14GW of transmission capacity by the end of January. Bill L 23 now puts most of them last in the queue. In Finland, data-centre projects with grid agreements add up to almost 5GW, Fingrid said in August. Meanwhile, the regulator has halted Google’s preparatory work at Muhos and Kajaani.
In Sweden, Brookfield has not solved power for its 750MW Strängnäs plan and is looking at other sites for parts of it. Building is slow even where power exists. Nscale’s Glomfjord site in Norway is six months behind schedule, after leaks in its cooling system and a fire, reports show.
Author: Akos Szima
See Also:
Finland’s Biggest Data Centres in 2026: What’s Live, Building, Planned and Delayed
Largest Data Centres in the World: The Gigawatt Club (2026)
What Country in Europe Has the Most Data Centres?
How We Checked This:
We used each operator’s own figures where it publishes them, from site pages, annual reports and press releases. Where it does not, we used trade press, as of November 4, 2026. “Capacity” is the figure each operator gives for sites it says are operating; most give IT load, and a few give power or contracted capacity. Download the data with a source for every figure (CSV).
Frequently Asked Questions:
On published figures, atNorth, with about 220MW across eight sites in Iceland, Sweden, Finland and Denmark. Green Mountain’s 143MW is the largest figure signed by customers at operating sites. Meta, Google and Microsoft publish no figures.
By published figures, Bitdeer’s Tydal site, which had 175MW of capacity as a bitcoin mine and is being converted to AI. Among sites rented to others, Green Mountain’s Hamar campus is the largest, with 90MW in operation.
CPP Investments owns about 51%, Equinix about 34% and Partners Group about 10%, with internal stakeholders holding the rest, after a $4 billion deal that closed on September 2, 2026.